Fintech Development Outsourcing Guide: Strategic Choices for 2026
Table of contents
Every fintech roadmap eventually surfaces the same high-stakes question: should you hire fintech developers in-house, pursue fintech software outsourcing through a specialized partner, or combine both models to move faster without losing control? For product and engineering leaders, this comes down to a pretty straightforward tradeoff: speed, risk, and cost.
This guide walks CTOs, product heads, and CFOs at Seed to Series B fintech companies through the full decision: why outsourcing makes structural sense in fintech, when and what to outsource, how to evaluate engagement models and select the right partner, and where a hybrid approach delivers the best balance of speed and control.
If the decision is live on your roadmap, the sections that follow give you the framework to make it, including a fast scorecard and a step-by-step vendor selection process.
Key takeaways:
- Outsourcing in fintech addresses a structural gap: the domain specialists delivery requires are scarce and slow to build internally.
- Open Banking layers, card issuance, reconciliation engines, regulatory reporting, and one-time compliance builds consistently suit external delivery.
- Risk algorithms, pricing models, and proprietary scoring logic belong in-house: IP exposure on these components directly affects competitive position.
- A hybrid model, with internal nucleus for core logic and compliance, external delivery for the rest, balances speed, control, and cost for most growth-stage teams.
- Partner selection is as consequential as model selection; vertical depth, team seniority, and documented governance practices determine whether the engagement delivers.
Why to outsource fintech development
Financial software outsourcing exists for a simple reason: fintech teams often need expertise they don’t have and can’t hire quickly. Payments, KYC, AML, and regulated data handling aren’t edge cases, they’re core parts of the product. Teams without that experience tend to discover the hard parts only after they’ve committed to timelines and architecture.
One common failure pattern is the compliance complexity trap. In reviews of struggling fintech initiatives, teams often underestimate their regulatory scope by 200-400%. What is planned as a short KYC implementation typically expands into extended vendor evaluation, prolonged integration and testing, unforeseen edge cases, and the need to build audit-ready evidence pipelines. These steps are unavoidable in production yet frequently excluded from early estimates.
The second constraint is the hidden specialist shortage. Fintech delivery cannot be solved by adding generalist engineers. It requires specialists with hands-on experience in payment flows, financial crime mitigation, and data consistency under financial workloads. These skills are scarce and slow to build internally.
The practical takeaway is selectivity. For many teams, a hybrid model retains core, differentiating components in-house and using fintech development outsourcing for compliance-heavy tasks. This approach allows them to deliver faster, more predictable outcomes without losing control. Let’s take a closer look at each model in detail.
In-house fintech development: When to own your critical systems
Building internally is still the best move when you control what truly differentiates your product. Choose in-house if the module houses your differentiating IP, latency is critical, or you have the runway and capacity to retain senior specialists. When these boxes are checked, a small nucleus team plus selective outsourcing can accelerate execution without giving up control.
Owning crown-jewel systems delivers tighter IP protection, direct compliance oversight, and faster secure iteration. In the case of startups, investors see it as a signal that your team has the technical chops to execute.
But these advantages come at a price: higher costs, slower ramp, and hidden overheads like audits, remediation, and specialized recruiting. To succeed, map your critical modules, hire fintech app developers for the primary team, embed compliance into every sprint, and standardize CI/CD and operational practices. Knowledge capture, training, and succession planning protect against turnover and skill gaps. Supplement with targeted consultancy support to bridge short-term peaks.
Bottom line:
Protect what’s critical in-house and selectively outsource the rest. Treat compliance and operational discipline as first-class priorities to balance speed, control, and risk when building a solution that can scale.
Outsourced fintech development
Outsourcing in fintech is not merely task delegation, particularly when it comes to crucial parts like payments. It’s a strategic lever to accelerate launches, access scarce expertise, and control burn. When weighing in-house versus outsourced development, the deciding factors are speed, specialized skills, and predictable economics. Outsourcing is ideal when deadlines are tight, risk engines stay internal, and specialized capabilities are needed faster than internal hiring allows.
Why fintech development outsourcing works
Such outsourcing gives rapid access to domain-proven squads, compliance playbooks, and pre-built connectors. Teams gain elastic capacity with significantly lower labor and infrastructure overhead, often saving 40-65% if compared to US-based in-house alternatives.
Key fintech services to outsource
Several recurring service categories fit the outsourcing model well: technically complex enough to benefit from specialist experience, but standardized enough that in-house builds add cost without strategic return.

Open Banking and PSD2 API layers
Account aggregation, consent management, and data-sharing interfaces that require certified connectivity but hold no proprietary logic
Card issuance and lifecycle management
Virtual and physical card programs, tokenization flows, and BIN sponsorship integrations
Reconciliation and settlement engines
End-of-day balancing, transaction matching, and exception-handling pipelines where domain-proven tooling cuts build time significantly
Regulatory reporting automation
MiFID II, Basel III, or GDPR evidence pipelines that require specialist knowledge but follow largely standardized implementation patterns
Identity verification
Biometric checks, liveness detection, and document authentication at the service layer, separate from the KYC decisioning logic you retain internally
Security testing
SAST/DAST, threat modeling, and compliance-ready penetration test reports, typically run by specialized firms on a recurring basis
When to outsource fintech development
Outsourcing works best for modules such as mobile apps, onboarding/KYC flows, or connector integrations, particularly when MVPs or features must ship in three to six months. It also makes sense when domain-specific expertise (like payment orchestration, fraud machine learning to detect fraud in real time, or DeFi security audits) is scarce, or when predictable vendor fees are preferable to permanent hires.
Pros and considerations
Outsourcing provides speed to market, access to specialist fintech experience, and cost predictability. However, trade-offs include reduced long-term control without explicit contracts, vendor management overhead, and potential quality variation. Governance typically requires ~0.4 internal FTE for a 3-engineer engagement and 1-1.75 FTE for 10-engineer squads, with nearshore vendors needing less synchronous coordination than offshore teams.
Risk management
Transfer clauses, encrypted repositories, and least-privilege access reduce IP and data exposure. SOC2/ISO certifications, pen-test reports, and right-to-audit provisions cover regulatory gaps. Pilots, code reviews, and retention clauses for key roles maintain quality and continuity.
Scenarios that favor outsourcing
The list below maps specific situations to the case for outsourcing and the risks each scenario carries.
| Scenario | Why outsourcing fits | Key risk to manage |
|---|---|---|
| Regulatory expansion into a new market | Regional certification knowledge, local banking integrations, and compliance documentation take years to build internally; established partners already hold the credentials | Data residency and IP ownership need contractual definition before work begins |
| One-time compliance build | External teams deliver PCI DSS, AML, or PSD2 implementations using pre-certified tooling, significantly faster than developing equivalent expertise from scratch | Audit evidence ownership must be explicitly assigned; the vendor builds, your team validates |
| Episodic workloads | QA automation cycles, data migrations, and compliance remediation sprints don’t justify the overhead of permanent headcount | Handover documentation and knowledge transfer should be contractual, not informal |
| Fixed cost ceiling | Nearshore and offshore rates reduce engineering costs substantially vs equivalent onshore hires without reducing delivery scope | Run a pilot before scaling. Cost savings are real, but so is quality variation |
| Tight launch timeline | Specialist squads reach production velocity faster than internal hiring cycles for senior fintech roles | Scope stability is a prerequisite. Late requirement changes carry significantly higher cost on fixed-price arrangements |
| Finite specialized phase | Skills like card scheme certification, core banking modernization, or embedded finance architecture are difficult to retain outside the phases that need them | Build knowledge transfer requirements into the contract from the start |
Choosing the right engagement model
Engagement can take the form of dedicated squads, project-based contracts, staff augmentation, or managed services. Different outsourcing models serve distinct needs, so the right one depends on your control requirements, project scope, and desired speed to delivery.
Outsourcing models: How and when to use each
| Model | Best for | Control level | Pricing logic | Typical timeline |
|---|---|---|---|---|
| Dedicated team | Ongoing product lines, continuous delivery, multisprint roadmaps | High through shared backlog and code ownership | Monthly per FTE with volume discounts | 4 to 12 weeks to full velocity |
| Project based | MVPs and clearly defined initiatives with stable requirements | Medium with changecontrol gates | Fixed price tied to milestones | 1 to 4 weeks to start, 1 to 6 months delivery |
| Staff augmentation | Rapid capacity addition for specific skills or sprints | Very high because your managers direct daily work | Hourly or monthly per engineer | 1 to 3 weeks onboarding |
| Managed service or platform component | Commodity capabilities such as KYC, payments routing, or analytics | Medium because the vendor runs the stack | Subscription or outcomebased | 2 to 6 weeks integration |
| Hybrid | In-house for key modules, outsource the rest | Variable | Blend | Custom |
What to look for in a vendor
Vertical depth
General fintech expertise is a baseline. Look for demonstrated delivery in your specific sub-sector: payments, lending, WealthTech, and InsurTech carry distinct regulatory and architectural demands.
Team seniority and composition
Request the working team profile before contracts are signed. Bench depth and whether the assigned specialists have worked together both affect output quality.
Stack compatibility
Mismatched tooling choices surface late and cost more to resolve than evaluating fit upfront.
Timezone model
Documented async-first practices for non-overlapping hours matter more than the size of the overlap window.
Elastic capacity
Ask how long previous engagements took to add an engineer mid-sprint, as vendor estimates are less reliable than references on this point.
Reference stage-fit
Enterprise and growth-stage references describe structurally different environments. Prioritize vendors with fintech clients at comparable scale and maturity.
Communication and reporting model
How a vendor structures updates, escalation paths, and issue visibility is as diagnostic as their technical credentials.
Quick-start outsourcing checklist
Strong governance is critical though. Here are a few musts to consider.
- Run a 4-6 week pilot delivering a small, integrated feature
- Define acceptance criteria for code quality, functionality, and integration
- Verify SAST/DAST pass and security pipeline adherence
- Review runbook completeness and operational procedures
- Confirm IP assignment, NDAs, and compliance documentation
- Establish weekly governance cadence and reporting
Make every interaction count
Oxagile combines flexible collaboration models with deep fintech expertise to build and scale solutions that perform seamlessly, stay secure, and minimize downtime.
Success snapshots that map to the decision
Real-world examples help make delivery decisions clearer. Below we share a few examples of how leading organizations structure their development using fully in-house teams or external partners.
A Polish bank, PKO Bank Polski, is a prime example of an outsourced fintech case. They used external development partners to accelerate the rollout of a corporate and mobile banking product. The external teams brought pre-certified connectors and compliance playbooks, which shortened integration testing by months and reduced risk in regional certification. Public case references and press coverage are available.
PayPal’s engineering approach tells a great in-house fintech development story. It highlights the value of keeping strategic systems internal. By maintaining control over its backend and orchestration logic, PayPal scaled rapidly and protected critical components such as latency-sensitive settlement processes and fraud controls. Strategic partners were used for peripheral features and UX acceleration, allowing the company to combine speed with strong in-house IP protection.
Decision framework and comparative matrix
A weighted scorecard can help guide delivery model decisions in a structured way. This compact, repeatable method evaluates in-house, outsourced, and hybrid approaches by comparing them across key factors like cost, time-to-market, expertise, control, scalability, and risk. Weighting each factor according to its importance provides a clear view of which model aligns best with a company’s stage and priorities.
Begin by trying to evaluate each option against key dimensions:
- Cost efficiency: how much TCO impact matters
- Time to market: how urgent the launch is
- Expertise access: whether you have the necessary domain specialists
- Control level: IP, data residency, and security needs
- Scalability: how quickly demand may spike
- Risk management: tolerance for vendor or operational risk
- Assign weights to each criterion (for example, cost 25%, time 20%, expertise 20%, control 15%, scalability 10%, risk 10%). Score in-house and outsourced options on a 1-10 scale, then multiply by the weights, and sum to generate a comparative score.
- The next step is to decide how to effectively manage time zones and governance.
- Nearshore (≤3-hour difference): low friction; expect 3-4 hours daily overlap, minimal governance overhead.
- Offshore (6-12-hour difference): plan 1-2 hours overlap; add ~1-2 hours per stakeholder weekly during ramp.
- Governance FTEs: for a 10-engineer outsourced squad allocate ~1-1.75 internal FTE, for 3 engineers consider ~0.4 FTE.
- Follow-the-sun teams: during early ramp, schedule two governance checks per week for the first six weeks, normalize afterwards.
- Finally, if the weighted score favors outsourced, run a small pilot (4-8 weeks) with clear acceptance criteria before scaling via dedicated teams. If in-house scores higher, prioritize hiring the nucleus team, protect runway, and consider backlogging auxiliary work for potential outsourcing.
- For growth-stage projects, the typical outcome is that outsourced solutions tend to score higher on cost, speed, and access to expertise. In-house wins on control and long-term cultural alignment. The hybrid model often scores best overall, offering a balanced approach across all criteria.
A step-by-step guide to choosing a partner for fintech outsourcing
1. Define your objectives
- Clarify which modules are in scope, what performance standards apply, and what “done” means at the contract level before any vendor conversations begin.
2. Domain-specific maturity assessment
- Ask for evidence of past delivery in your specific sub-sector rather than fintech broadly. Runbooks and handover docs reveal operational discipline more reliably than case studies.
3. AI and modern tool integration evaluation
- Confirm whether AI-assisted development tools are part of their workflow and whether code is processed through third-party models, which carries direct IP exposure risk in fintech contexts.
4. Regulatory and security audits
- Conduct an audit of security measures and regulatory compliance. Request actual audit reports rather than summaries and extend the review to subcontractors because a vendor’s security posture is only as strong as the weakest third party in their supply chain.
5. Communication and governance
- Establish governance mechanisms and a communication schedule. Define decision rights, escalation paths, and a reporting format tied to your actual objectives before the engagement starts.
Bottom line:
Outsource fintech development strategically for non-critical, compliance-heavy, or time-sensitive work to gain speed, specialized expertise, and cost predictability and, at the same time, keep critical systems in-house.
Hybrid fintech development as the best-of-both-worlds strategy
- For many decision makers, in-house vs outsourcing software development in fintech isn’t an either/or decision. When growth is non-linear and regulatory compliance is non-negotiable, a hybrid model lets you move fast without losing control. You retain your “brain trust” and extend reach through proven external capacity.
Why hybrid works and when to use it
- The hybrid model keeps strategic control of critical IP and engages external teams for delivery and specialized expertise. It balances speed, cost, and governance, allowing companies to scale securely without sacrificing agility.
- Hybrid works best when your product combines differentiating IP and heavy compliance with frequent launches, or when follow-the-sun development is needed and sensitive services remain internal.
How to design a hybrid team
- Start by mapping high-value versus standard modules. Build a nucleus team in-house, typically a lead architect, compliance/risk lead, and senior backend engineer. Extend delivery through partner lanes for non-core features or areas that require external expertise.
- Maintain a single backlog and release trains, shared CI/CD pipelines, and unified coding standards. Governance should include weekly risk reviews, automated audit evidence capture, and exit or handover plans for every vendor lane. For pilot projects, run a six-to-eight-week engagement with predefined deliverables to set clear expectations.
- What should you outsource? Typical acceleration layers include mobile development, QA automation, data pipelines, and admin tools. In other words, tasks that benefit from domain-proven external squads and follow-the-sun coverage.
- For example, you might outsource a single accelerator, such as an onboarding flow, and recruit two to three in-house roles. This preserves ownership of architecture, compliance, and scoring logic and speeds up feature delivery through external teams. Across the hybrid setup, hire fintech software developers for the main team to anchor strategic systems. Regional rates vary, providing flexibility and cost efficiency.
Governance and best practices
- Managing hybrid teams takes deliberate effort. One product owner should have end-to-end accountability, supported by shared sprint rituals to keep everyone aligned. Tooling also has to be unified across the team. For instance, a single Jira project, a Git org with branch protection, and centralized CI visibility help maintain consistency. Weekly governance reviews provide security, compliance, and audit readiness. Meanwhile vendor continuity plans with backup personnel and knowledge checkpoints keep the operation resilient.
- When executed thoughtfully, the hybrid strategy is more than “mix and match”. It delivers speed, resilience, and capital efficiency and safeguards critical intellectual property and regulatory compliance.
Bottom line:
Use a hybrid model to protect main IP and compliance, using external teams for supporting modules delivery to achieve speed, scalability, and operational resilience without sacrificing control.
Case in point: Scaling multi-region accounting software
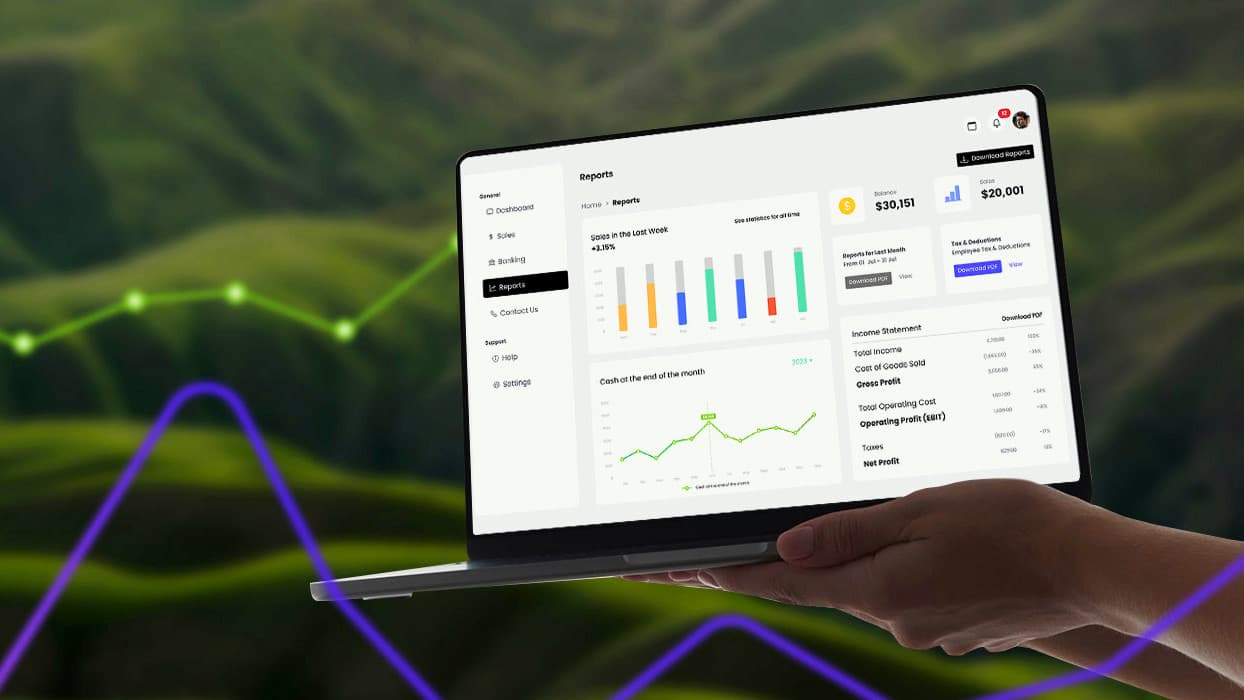
A leading accounting platform needed to expand into Europe without rebuilding its mission-critical systems. Legacy infrastructure limited scalability, compliance, and localization.
Our solution and impact:
- Multi-region AWS architecture with multi-tenancy
- Migration to .NET 8 and containerized workloads for faster CI/CD
- Integrated banking providers (Yodlee, Plaid, SaltEdge) for automated transactions
- Localized EU compliance features (VAT, Company ID)
- UX redesign for smoother navigation and workflows
- Comprehensive reporting and audit trail capabilities
Result: Scalable, compliant, and efficient financial operations across multiple regions, with a foundation for future payment innovations.
Final stage-aware recommendations
- One insight surely stands out in fintech development: successful companies outsource more than you might expect, but they do it surgically. They protect the 10-15% of their system that drives real competitive advantage, typically risk algorithms, pricing models, or unique regulatory workarounds. Everything else is infrastructure that can be delivered faster and more efficiently by specialized teams.
- Before deciding what to keep in-house and what to outsource, identify the parts of the product that actually set you apart. If a competitor copied them tomorrow, would it matter? Those are the areas worth owning. This stage-aware approach helps fintech leaders balance speed, control, and risk as they scale effectively.
From concept to scale, with confidence
Partner with Oxagile to design, implement, and optimize fintech solutions that combine robust architecture, full observability, and operational reliability.
FAQ
How do I choose the right partner for fintech development?
Beyond cost, evaluate fintech expertise, compliance track record, scalable architecture skills, and supported governance models. Consider experience with fintech software outsourcing, a portfolio of successful fintech projects, and high client retention. Piloting early allows teams to validate quality, speed, and integration. Many outsourced MVPs are 30–50% faster than building in-house.
Can outsourced teams handle strict compliance requirements?
Yes, if you select the right partner. Modern fintech software outsourcing models often include compliance officers and certified engineers familiar with PCI DSS, PSD2, and SOC 2 frameworks. Providers in hubs like Eastern Europe or Singapore routinely build for multi-jurisdictional compliance, reducing exposure to costly errors.
How do investors view outsourcing vs in-house fintech development?
Investors focus on two things: speed to market and protection of intellectual property. Early-stage VCs often encourage teams to outsource fintech development, as it accelerates proof-of-concept and product validation. At Series B and beyond, boards typically expect evidence of internal technical depth. A hybrid strategy reassures investors by balancing rapid delivery with long-term control.